

Común: Your money, your way
by Comun
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
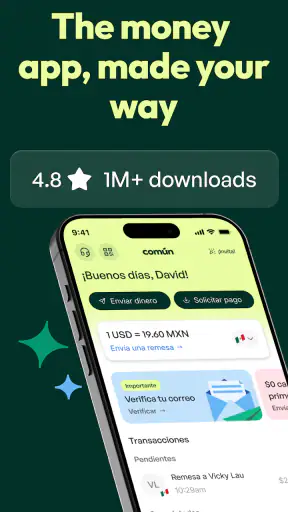
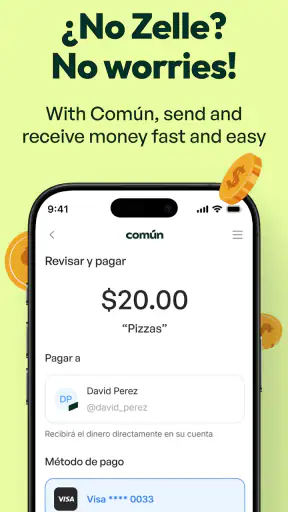
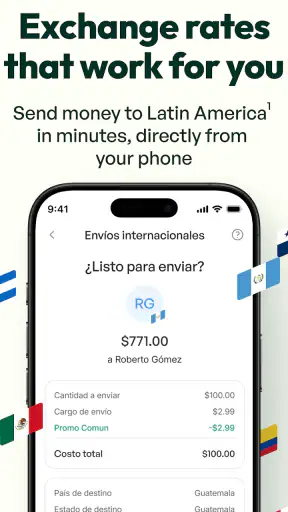
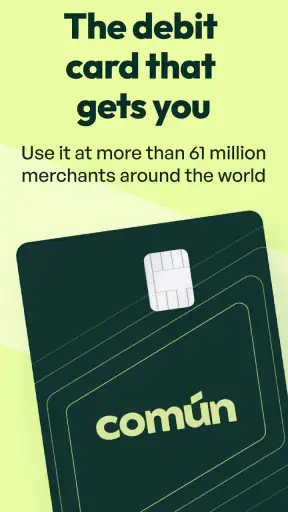
When money moves between people who share a home, the difficult part is often not the payment itself. It is remembering who paid, choosing a practical way to send funds, and keeping personal finances separate while still handling everyday expenses together. I found Común most interesting in that space: it is a free finance app from Comun that lets you pay people, send money to Latin America, and use a Visa debit card. That combination makes it more useful than a simple transfer tool, although it also means you should think carefully about who controls the account and how a shared household will use it.
I approached it as an app for real routines rather than as a novelty. A household might use one person’s account for a grocery run, send money to a relative abroad, or give an adult family member a separate way to spend without handing over access to someone else’s banking details. Those are different jobs, and Común is strongest when the boundaries between them are clear. It is less convincing if you expect it to become a complete household budgeting system or a replacement for every financial service you already use.
How Común fits into a shared household
Imagine a normal weekday: one person is working late, another is buying food, and a relative in Latin America needs money sent before the evening. In that situation, having payment, international transfers, and a Visa debit card in the same finance app can reduce the number of separate steps. I like that the app’s purpose is easy to understand. It is not trying to make a shared device into a shared bank account; it gives an individual a way to handle several common money movements from one place.
The distinction matters. If several people use the same phone, I would not treat Común as a communal wallet by default. A financial app should remain tied to the person responsible for it, even when the spending benefits everyone in the home. The cleaner arrangement is for one adult to manage the account and communicate about a purchase, while other household members use their own payment methods or receive money separately. That approach avoids the confusion that comes from passing a logged-in finance app around.
For a couple, roommates, or relatives sharing expenses, the most useful workflow is simple: agree in advance what the account is for, use it for those agreed expenses, and keep personal spending outside that arrangement. For example, a household could decide that Común covers groceries and a particular family transfer, while rent, subscriptions, and private purchases stay in each person’s usual account. The app can support the movement of money, but it cannot replace a conversation about responsibility.
The key household rule is to share a purpose, not unrestricted account access. That is especially important on a shared tablet or phone. I would avoid leaving the app open, saving access details where another person can see them, or assuming that a trusted family member should automatically be able to send money. Convenience is valuable, but financial boundaries are more valuable.
What setup feels sensible
During setup, I would begin with the person who will actually own and operate the account. That sounds obvious, but it prevents a common household mistake: creating an account around a shared phone number, a jointly used email address, or a device that changes hands frequently. Account ownership should be understandable later, particularly when a transfer needs to be checked or a card transaction needs attention.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I would also decide where Común belongs in the household’s financial system before using it actively. Is it mainly for sending money to Latin America? Is the Visa debit card intended for everyday purchases? Is it a convenient way to pay another person? Each answer leads to a different routine. Treating every feature as part of one large shared balance can make it harder to tell whether a payment was personal, household-related, or intended for someone overseas.
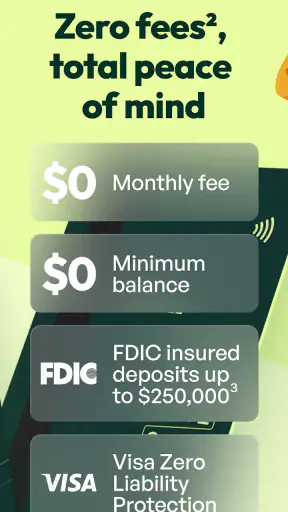
The app is free, which lowers the barrier to trying it. Still, free access should not be confused with unlimited suitability for every financial task. I would read the details shown during each relevant transaction and check the destination, recipient, and amount before confirming. International money movement deserves particular care because a mistake can be more difficult to unwind than an ordinary local purchase.
Another practical boundary is the card. A Visa debit card can be convenient for the account holder, but it should not be treated like a family card unless everyone understands who is accountable for its use. If the card is carried by one person but paid for from money contributed by several people, keep a basic record of contributions and purchases. Común may make the payment easy; the household still needs its own method for settling disagreements.
Coordinating payments without creating confusion
I see two strong coordination uses. The first is a direct payment between people. That works well when the recipient and purpose are obvious: settling a meal, reimbursing a household purchase, or sending a small amount to someone who needs it. The second is sending money to Latin America, where the app’s focus can be more relevant than a general-purpose payment service that you only use occasionally.
For recurring household costs, I would avoid relying on memory. Before sending money, write a short note in whatever household system you already use, such as a shared message thread or a simple private list: date, purpose, sender, and recipient. This is not glamorous, but it prevents the classic problem of someone asking whether a transfer was already made. The app handles the transaction; the separate note handles the household context.
A useful habit is to confirm the recipient using more than a familiar name. People can have similar names, and contacts can be saved inconsistently. I would pause at the final review screen, check the destination details, and only then authorize the payment. This extra moment is particularly worthwhile when a device is being used by several people and one person is acting on another person’s verbal request.
For international transfers, I would agree on the exact amount and timing before opening the app. The sender and recipient may be thinking in different currencies or may have different expectations about what the recipient should receive. Común can make the sending step more direct, but it cannot resolve an unclear agreement. A message such as “I am sending this amount for this purpose today” is a small improvement that prevents avoidable tension.
The Visa debit card also changes the coordination question. A transfer is usually deliberate; a card purchase can feel immediate and routine. If the card is used for shared groceries or transport, establish a spending category and review purchases regularly. If it is used for private spending, keep it private. Mixing both without a clear rule makes the account history harder to understand and weakens the value of having one place for several types of money movement.
Age, trust, and account responsibility
Común has an Everyone content rating, but that should not be read as a recommendation for unsupervised financial use by every age group. A content label describes the app’s general audience, while money responsibility depends on maturity, identity, and the account holder’s ability to understand transfers and card spending. I would be comfortable discussing the app with a teenager as part of financial education, but I would not hand over an adult account simply because the app is easy to find or simple to operate.
For an older child or young adult, a safer household approach is to define a narrow purpose. Perhaps the person receives a specific amount for transport or food and learns to track those purchases. The adult account holder should remain clear about what the money is for and who is responsible for the card. This is less about restricting the person and more about making the learning goal visible. If the young user needs independent financial ownership, a service designed specifically around that situation may be a better fit.
Trust also matters between adults. A spouse, roommate, or parent may be completely trustworthy and still not be the right person to operate another adult’s financial account. Shared devices make this easy to blur. I would use separate device access where possible, avoid discussing sensitive details in front of people who do not need them, and never assume that a household relationship removes the need for consent before sending money.
When a relative abroad is involved, communication becomes just as important as the app. Confirm the recipient’s details through a channel you already trust, especially if the request arrived unexpectedly. A familiar family story can still be used in a fraudulent message. My practical view is that Común should be the final step after the request has been verified, not the place where you try to decide whether the request is genuine.
What I liked and where I would be cautious
The clearest strength is focus. Común connects person-to-person payments, transfers to Latin America, and a Visa debit card without forcing me to think of them as unrelated tools. For someone who regularly sends money across borders or wants a dedicated way to pay, that can be more convenient than maintaining several apps. The free price also makes experimentation easier, and the app’s Everyone rating makes it approachable for households discussing it together.
Its public reception is encouraging: Común has an average rating of 4.8 from around twenty-two thousand ratings, with roughly two thousand seven hundred written reviews. It has also passed half a million installs, so it is not an obscure experiment that only a handful of people have tried. Those figures do not tell me whether every transaction will be smooth, but they do suggest that many users find the basic experience worthwhile.
My caution is about scope. A payment app is not automatically a shared budget planner, a family allowance system, or a replacement for a traditional bank account. If your priority is detailed household categorization, joint financial visibility, scheduled bill management, or sophisticated spending analysis, a dedicated budgeting tool or your existing bank may serve you better. Común makes money movement its central experience, and that is both its appeal and its limit.
I would also compare it with the alternatives based on the job rather than on brand familiarity. For a local reimbursement, a general payment service you and the recipient already use may involve less setup. For a debit card, a conventional bank may offer a broader account relationship. For international transfers, a specialist service may be preferable if it provides the corridor, exchange information, or recipient options you specifically need. Común becomes the better choice when combining its core functions in one app saves you repeated effort.
Version 2.29.0 is the current version, and the app requires at least iOS or Android 10. That makes device compatibility worth checking before planning a household workflow around it, particularly if an older shared phone is involved. I would not replace a working payment method on a family member’s device until I had confirmed that the device can run the app comfortably and that the person understands the new routine.
Who should use it—and who should skip it
I would recommend Común to an adult who wants a straightforward finance app for paying people, sending money to Latin America, and using a Visa debit card. It is especially appealing when those needs overlap. A person who sends support to relatives abroad and also wants a separate card for everyday spending may appreciate having both functions close together rather than switching between unrelated services.
It can also work well in a household with clear roles. One adult can own the account, use it for agreed expenses, and coordinate transfers through a shared conversation. The important part is not giving everyone access; it is making sure everyone knows what the account is being used for. That structure keeps the app useful without turning it into an unclear pool of money.
I would skip it as the main household solution if your first requirement is true joint control. It is also not my first choice for someone who wants extensive budgeting tools, a complete banking relationship, or a purpose-built supervised account for a minor. In those cases, another type of financial product may match the responsibility and visibility you need more closely.
I would be cautious if your household frequently sends urgent transfers based on messages that are hard to verify, or if several people insist on using one logged-in device. Neither problem is solved by a clean interface. The right answer may be a stricter family process, separate accounts, or a service with controls designed for the specific arrangement.
My household verdict
After looking at Común through the lens of shared living, I see it as a practical personal finance app that can support household coordination when the boundaries are deliberate. Its combination of payments, Latin America transfers, and a Visa debit card gives it a clear everyday role. I like the convenience, the free entry point, and the fact that it can serve both local interactions and family support across borders.
I would use it with one accountable adult as the owner, a defined purpose for the balance, and a quick confirmation routine before every important transfer. I would not pass the phone around as if the account were a communal object, and I would not assume that an Everyone rating makes unsupervised use appropriate for children. Those decisions are part of using a financial app responsibly, not criticisms of the app itself.
For the right person, Común is most valuable as a focused bridge between everyday payments, international family support, and card spending. It is not a universal answer for household finances, but it does not need to be. If your needs fit that combination and you can keep ownership and communication clear, I think it is worth trying. If you need deep joint budgeting or formal age-based controls, I would look elsewhere before making it the center of your family’s money routine.
Pros
- Clear overview of spending, income, and financial activity in one place.
- Designed to help users make more informed everyday money decisions.
- Useful tools for organizing personal finances and tracking money habits.
- Clean, approachable interface suitable for users with limited finance experience.
- Can make routine money management more convenient than using separate tools.
Cons
- Some features may depend on supported banks, regions, or account types.
- Financial data availability can vary depending on synchronization and provider access.
- Users may need time to configure categories, goals, or personal preferences.
- A finance app may not replace professional advice for complex money decisions.
- Handling sensitive financial information requires careful attention to privacy settings.
FAQs for Común: Your money, your way
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users manage everyday money in one place. Depending on the services available in your region, it may provide tools for organizing finances, monitoring transactions, making payments, or accessing related financial products. Before downloading, check the official listing to confirm which features and account types are currently supported in your country.
Is Común safe to use for managing my money?
Financial apps require careful consideration because they may handle sensitive personal and payment information. Before creating an account, review Común’s privacy policy, security information, permissions, and identity-verification requirements. Use a strong, unique password, enable any available security options, and download the app only from an official store. Never share verification codes or login details with another person.
Do I need to meet specific requirements to use Común?
You may need to meet eligibility requirements before using all of Común’s services. These can include being a certain age, living in a supported country, providing a valid phone number or email address, and completing identity verification. Some features may also require an approved account or additional documentation, so availability can differ depending on your location and personal circumstances.
Does Común charge fees for its services?
The cost of using Común can depend on the specific service, transaction type, account plan, and country where you live. Some features may be free, while others could involve subscription charges, transfer fees, withdrawal costs, exchange-rate margins, or third-party charges. Read the current fee schedule and terms carefully before transferring money or activating a paid feature.
Can I use Común if I have a problem with a transaction or account?
Común should provide in-app or online support for issues such as failed transactions, account access, verification delays, or suspicious activity. However, response times and available support channels may vary. Keep transaction references, screenshots, and relevant dates when contacting support, and report unauthorized activity immediately. Do not attempt to resolve financial disputes through unofficial social-media accounts or unknown contacts.

Común: Your money, your way
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via ayuda@comun.app, visit https://www.comun.app, or review their https://www.comun.app/legal/privacy-policy.










